To make a realistic budget and save consistently, start by tracking all income and expenses for a month to understand your financial flow. Categorize your spending into fixed (rent, loans) and variable (groceries, entertainment). Then, allocate funds based on priorities, like the 50/30/20 rule (needs/wants/savings). Set clear, achievable saving goals, whether for an emergency fund, travel money, or a down payment. Regularly review and adjust your budget to reflect changes in income or spending habits, ensuring it remains a flexible tool rather than a rigid restriction. This iterative process helps build a simple monthly budget that you can maintain and leads to consistent savings.
Many people approach budgeting with a sense of dread, often viewing it as a restrictive chore rather than an empowering financial tool. The common narrative suggests a rigid system of deprivation, leading to frustration and abandonment. However, the most effective budgets aren’t about cutting every pleasure; they’re about understanding your money, aligning spending with values, and creating a sustainable plan.
Consider Sarah from Manchester, a freelancer who used to juggle irregular income with unpredictable expenses. She tried several complex budgeting apps, only to give up after a few weeks because they felt too time-consuming. Her breakthrough came when she simplified her approach, focusing on a handful of key categories and automating her savings. This shift transformed her relationship with her finances, enabling her to build a simple monthly budget that she could genuinely maintain, helping her save money for a deposit on a flat.
This article will guide you through building a simple, maintainable monthly budget. We’ll focus on practical steps that resonate whether you’re managing household finances in Berlin, a young adult in Madrid, or a family in Chicago, emphasizing strategies for personal finance and saving money without feeling overwhelmed.
Understanding Your Financial Landscape
Before you can effectively build a simple monthly budget that you can maintain, you need a clear picture of your current financial situation. This isn’t about judgment, but about honest assessment. Think of it as mapping your financial terrain before embarking on a journey. This initial phase is crucial for establishing a realistic foundation for your budget.
Start by gathering all your financial statements: bank accounts, credit cards, loan documents (mortgage, student loans, car loans), and investment accounts. The goal is to identify your total income from all sources – salary, freelance work, side gigs, rental income, or benefits. For many, especially freelancers or those with variable income, this might mean averaging income over a few months to get a more accurate picture.
Next, meticulously track every single expense for at least one month. This can be done manually with a notebook, using a spreadsheet, or by leveraging banking apps that categorize spending automatically. Don’t skip small purchases; those daily coffees or impulse buys add up quickly and often reveal hidden spending patterns. This exercise often highlights areas where money is leaking unknowingly, forming the bedrock for your ability to build a simple monthly budget that you can maintain.
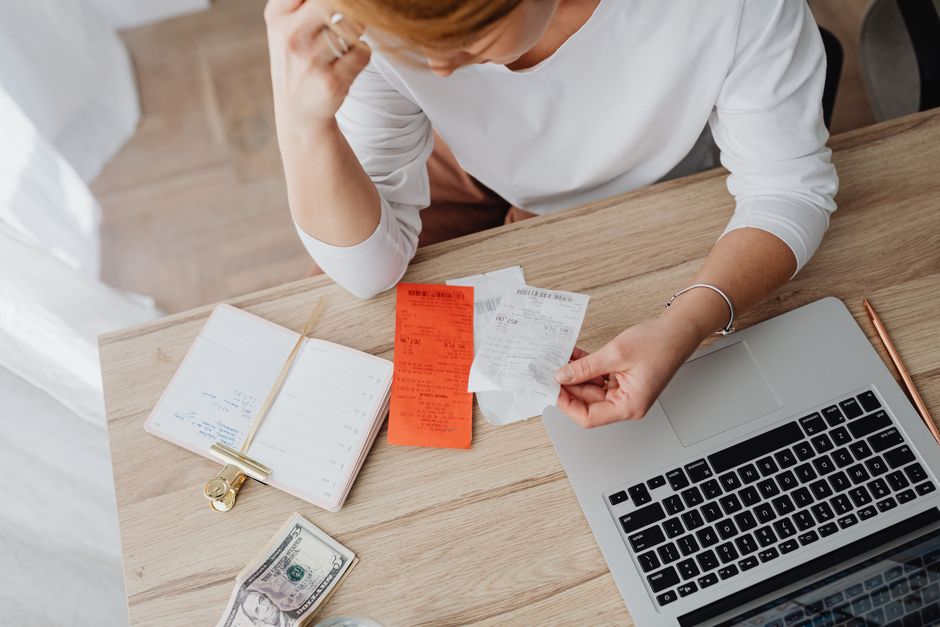
A person diligently tracking expenses on a laptop, symbolizing the initial step of understanding your financial landscape.
Practical Steps to Build Your Maintainable Budget
Once you have a clear picture of your income and expenses, it’s time to construct your budget. The key here is simplicity and flexibility, ensuring it’s a tool you’ll actually use, not just a document you create once and forget.
Smart Travel: How to Compare Travel Cards, Fees, and Exchange Rates Effectively
1. Categorize Your Spending
Group your expenses into logical categories. A common approach is:
- Fixed Expenses: These are costs that are generally the same each month and are non-negotiable (e.g., rent/mortgage, loan repayments, insurance premiums, subscriptions like Netflix or Spotify).
- Variable Expenses: These costs fluctuate each month and offer more flexibility for adjustment (e.g., groceries, dining out, entertainment, fuel, clothing, travel money).
- Savings & Debt Repayment: This category should include dedicated allocations for an emergency fund, specific saving goals, and extra payments towards debt beyond the minimums.
2. Set Realistic Goals
What do you want your money to do for you? Whether it’s building an emergency fund of three to six months’ living expenses, saving for a down payment on a home, funding a dream holiday to Italy, or paying off student loans, specific goals provide motivation. Break large goals into smaller, achievable monthly targets. This makes the journey less daunting and helps you visualize progress towards personal finance and saving money.
3. Choose a Budgeting Method
There isn’t a one-size-fits-all budget. Explore methods that suit your personality and lifestyle:
- The 50/30/20 Rule: Allocate 50% of your income to needs, 30% to wants, and 20% to savings and debt repayment. This is a straightforward framework for many households.
- Zero-Based Budgeting: Every euro, pound, or dollar is assigned a job. Your income minus your expenses (including savings) should equal zero. This method requires more detailed tracking but ensures every penny is accounted for.
- Envelope System: For cash spenders, this involves allocating physical cash into envelopes for different variable spending categories (e.g., ‘Groceries,’ ‘Entertainment’). Once an envelope is empty, you stop spending in that category until the next budget cycle.
4. Automate Your Savings
One of the most powerful strategies to build a simple monthly budget that you can maintain is to automate your savings. Set up automatic transfers from your checking account to your savings account, retirement fund, or investment accounts on payday. Treat savings as a fixed expense – pay yourself first. This removes the temptation to spend money before it even hits your main account.
5. Track and Adjust Regularly
A budget is a living document. Life happens. Your income might change, unexpected expenses arise (like car repairs), or your saving goals evolve. Make it a habit to review your budget at least once a month, perhaps before payday. See where you overspent, where you underspent, and what adjustments are needed. This continuous feedback loop is essential for maintaining your budget and ensuring it remains a practical tool for personal finance and saving money.
6. Plan for Irregular Expenses
Not all expenses are monthly. Annual insurance premiums, holiday gifts, car maintenance, or even larger purchases like a new appliance in Poland or Germany, can derail a budget if not anticipated. Create a sinking fund – a separate savings pot – for these irregular but predictable costs. Divide the total annual cost by 12 and save that amount monthly.
Budgeting Tools and Methods Comparison
Choosing the right tool can significantly impact your ability to maintain your budget. Here’s a brief comparison of common options:
| Method/Tool | Pros | Cons | Best For |
|---|---|---|---|
| Spreadsheets (Excel/Google Sheets) | Highly customizable, free, detailed tracking, good for visual learners. | Manual data entry, can be time-consuming to set up and maintain. | Detail-oriented individuals, those with complex finances, or who enjoy manual control. |
| Budgeting Apps (e.g., YNAB, Mint, Rocket Money) | Automated transaction import, categorization, goal tracking, alerts, often available in multiple GEOs (US, UK, Europe). | Subscription fees (for premium features), less control over categorization sometimes, data privacy concerns. | Tech-savvy users, those who prefer automation, busy individuals wanting quick insights. |
| Pen and Paper | No cost, simple, tactile, good for visual learners and minimalists. | Manual calculations, prone to errors, no automation, difficult to track historical data over long periods. | Beginners, those on a very tight budget, or individuals who prefer simplicity. |
| Bank Budgeting Features | Often free with your existing bank account, integrated with your transactions, provides basic spending insights. | Limited features compared to dedicated apps, less customization, may not link all external accounts. | Those seeking basic insights without extra apps, customers of major banks like Lloyds Bank (UK) or Deutsche Bank (Germany). |
A person comparing different budgeting app interfaces on a tablet, showcasing options for financial management.
Common Mistakes to Avoid
Even with the best intentions, budgeters often fall into common traps that lead to discouragement and abandonment. Being aware of these pitfalls can help you navigate your personal finance journey more smoothly.
Official-Zonky: The Ultimate Guide to Smart Investing in Peer-to-Peer Lending
A primary mistake is being overly restrictive from the outset. If your budget feels like a straitjacket, you’re more likely to rip it off. Instead of slashing all discretionary spending, aim for gradual adjustments. Cut back in one or two areas initially, like reducing how often you eat out or delaying a major purchase. This incremental approach makes the budget feel more achievable and helps you build momentum.
Another frequent error is neglecting to track every expense. It’s easy to overlook small, seemingly insignificant purchases, but these ‘micro-transactions’ accumulate rapidly. The daily coffee, the quick snack, or the small online subscription can seriously impact your budget. Be diligent about tracking everything, as these minor expenditures often reveal areas where you can effortlessly save money.
Ignoring irregular expenses is another common pitfall. Many people budget only for monthly costs, forgetting about annual insurance payments, holiday gifts, or car maintenance. These unexpected large expenses can completely derail a well-intentioned budget. Establishing sinking funds for these costs is crucial for maintaining stability. This also applies to managing different currencies; if you regularly deal with international payments, understanding exchange rates and payment safety can prevent hidden fees from impacting your budget.
Finally, a budget that’s never reviewed or adjusted is essentially useless. Life changes – your income might fluctuate, you might have a new family member, or your priorities could shift. Treat your budget as a living document, not a static spreadsheet. Regularly setting aside time each month to review and tweak your categories, goals, and allocations ensures it remains relevant and effective for your ongoing personal finance and saving money efforts.
Frequently Asked Questions About Building a Budget
How long does it take to create a functional budget?
While the initial setup can take a few hours to gather information and categorize expenses, a functional budget typically takes 2-3 months to truly settle in. This period allows you to track spending accurately, identify patterns, and make necessary adjustments to ensure it’s realistic and sustainable for your lifestyle.
What is the most effective way to track my spending?
The most effective way depends on your preference. Many find budgeting apps like YNAB or Mint efficient for automated tracking. Others prefer a simple spreadsheet for full control, or even a pen and paper for a tactile approach. The key is consistency and choosing a method you’ll stick with daily or weekly.
How much should I save each month?
A common guideline is to aim for at least 20% of your net income for savings and debt repayment, following the 50/30/20 rule. However, the ideal amount varies based on your income, expenses, and financial goals, such as building an emergency fund or saving for a down payment. Prioritize an emergency fund first.
What if my income is variable, like a freelancer’s?
If you have variable income, consider budgeting based on your lowest expected monthly income. When you have ‘extra’ income, allocate it towards savings, debt repayment, or an irregular expenses fund. Averaging your income over the past 3-6 months can also help create a more stable baseline for your budget.
Should I include my subscriptions in my budget?
Absolutely. Subscriptions, from streaming services to gym memberships, are recurring expenses that can significantly impact your budget. Categorize them as fixed expenses and review them periodically to ensure you’re still using and getting value from each service, helping you find areas to save money.
Building a simple monthly budget that you can maintain is not about financial gymnastics; it’s about thoughtful planning and consistent application. By understanding your cash flow, setting clear goals, choosing a method that works for you, and avoiding common pitfalls, you can improve your personal finance journey and significantly improve your ability to save money. For more practical money guides, explore the resources on GoTrendlin.