To plan a memorable trip without overspending while staying protected, choosing the right travel insurance for flights, health, and baggage is crucial. Start by assessing your trip’s specific risks: destination, activities, and duration. For flights, consider cancellation and delay coverage. For health, ensure comprehensive medical and emergency evacuation benefits that suit your global destination. For baggage, look for coverage against loss, theft, or damage. Prioritize policies that offer flexibility and clear terms, balancing cost with adequate protection to ensure truly affordable travel planning. Always compare several providers to find a plan that aligns with both your budget and your travel needs, making informed choices for peace of mind.
A few years ago, a colleague recounted a harrowing experience: a sudden appendicitis attack during a business trip to Madrid. Without travel insurance, the medical bills alone would have been ruinous, let alone the emergency flight home. It’s a stark reminder that even the most meticulously planned trips can take unexpected turns. While we all hope for smooth sailing, the reality of travel often involves unforeseen bumps – from a delayed flight disrupting carefully laid plans for a European city break to a lost suitcase on a transatlantic journey to the US, or even a more serious health incident while exploring the historic streets of Rome or Berlin.
This isn’t about fear-mongering; it’s about practical preparedness. Think of travel insurance as your financial safety net, allowing you to embrace new experiences, knowing you’re protected against common travel pitfalls. It’s a fundamental component of truly affordable travel planning, ensuring that unexpected costs don’t derail your adventure or your bank balance.
The Non-Negotiable Necessity: Understanding Why Travel Insurance Matters
For many, the idea of paying for something you hope never to use feels counterintuitive. However, the value of travel insurance becomes incredibly clear when things go awry. Whether you’re heading off for a solo adventure, a romantic getaway, or a family vacation, the peace of mind it offers is invaluable. It transforms potential financial disasters into manageable inconveniences.
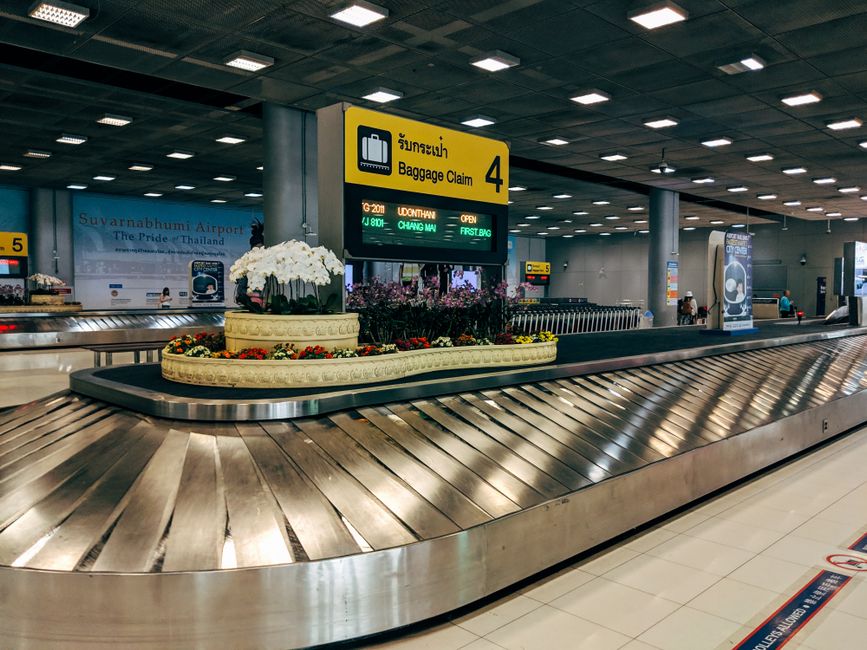
Consider a flight cancellation: without insurance, you might be scrambling to rebook expensive last-minute tickets or forfeit non-refundable accommodation. A medical emergency abroad can quickly escalate into five-figure bills, especially in countries like the US where healthcare costs are notoriously high. Even a lost checked bag, while not life-threatening, can significantly disrupt your trip, forcing you to buy essential items when you should be enjoying your destination.
Choosing travel insurance for flights, health, and baggage isn’t merely about ticking a box; it’s about making an informed decision that protects your investment and well-being. It’s particularly vital when planning international trips, given the varied healthcare systems and consumer protections across different countries. For travelers from the US, UK, Germany, France, Italy, Spain, and Poland, understanding the nuances of how your domestic insurance extends abroad (or doesn’t) is a crucial first step.
Your Step-by-Step Guide to Choosing Comprehensive Travel Insurance
Finding the right travel insurance doesn’t have to be complicated. It requires a clear assessment of your needs and an understanding of what different policies offer. Here’s how to approach it:
Experience Smooth Journeys and Worldwide Travel with Singapore Airlines
1. Assess Your Trip’s Specific Risks
Start by considering your destination, activities, and the duration of your trip. Are you planning adventurous activities like skiing or scuba diving that might require specialized coverage? Is your destination known for high crime rates or political instability? Traveling to remote areas might necessitate higher emergency evacuation coverage. A short city break to Paris or Rome in the shoulder season will have different risk profiles than a month-long backpacking trip across South America.
2. Understand Different Policy Types
There are generally three main types:
- Single-Trip Policies: Ideal for one-off vacations, offering coverage for a specific duration.
- Multi-Trip (Annual) Policies: Suitable for frequent travelers making several trips within a year. Often more cost-effective if you travel more than twice annually.
- Specialty Policies: Tailored for specific needs, such as adventure travel, long-term expatriate health, or cruises.
3. Prioritize Flight and Trip Interruption/Cancellation Coverage
This is critical for protecting your financial investment in non-refundable flights, hotels, and tours. Look for coverage that includes:
- Trip Cancellation: Reimburses prepaid, non-refundable expenses if you cancel for a covered reason (e.g., illness, family emergency, severe weather).
- Trip Interruption: Covers costs if your trip is cut short due to a covered event.
- Flight Delay: Provides reimbursement for unexpected expenses (e.g., meals, accommodation) during significant delays.
- Missed Connection: Important for complex itineraries with multiple flights, especially when exploring multiple European cities.
4. Ensure solid Health and Medical Coverage
This is arguably the most vital component, especially for international travel. Your domestic health insurance might offer limited or no coverage abroad. Key considerations:
- Emergency Medical Expenses: Covers treatment for unexpected illnesses or injuries. Look for high limits, generally €100,000 to €250,000+ for international travel.
- Emergency Evacuation/Repatriation: Covers the cost of transporting you to a suitable medical facility or back home. This can be extremely expensive (hundreds of thousands of euros) and is non-negotiable.
- Pre-existing Conditions: Many policies exclude these. If you have pre-existing conditions, seek a policy that explicitly covers them, often requiring a medical screening.
5. Safeguard Your Belongings with Baggage Coverage
While often secondary to health, lost or stolen luggage can significantly impact your trip enjoyment. Look for:
- Lost/Stolen Baggage: Reimburses you for the value of your lost or stolen items. Check per-item limits and total coverage.
- Delayed Baggage: Provides funds to buy essentials (toiletries, clothes) if your bags are delayed for several hours or more.
- Valuables: If you’re traveling with expensive items (laptops, cameras, jewelry), ensure they are specifically covered, as general baggage limits might be too low. You might need a separate rider or homeowner’s insurance policy.
6. Understand Exclusions and Policy Fine Print
This is where many travelers make mistakes. Read the policy document thoroughly. Common exclusions include:
- Acts of war or terrorism (though some policies now offer coverage).
- Incidents related to drug or alcohol abuse.
- Participation in high-risk sports not declared.
- Unattended belongings (e.g., leaving a bag on a beach).
- Certain natural disasters in specific regions.
7. Compare Providers and Get Multiple Quotes
Don’t settle for the first quote. Reputable insurers in Europe and North America include Allianz Travel Insurance, AXA Assistance, World Nomads, and SafetyWing. Use comparison websites, but always visit the insurer’s direct site to read the full policy document. For affordable travel planning, weighing the benefits against the cost is essential.
Explore New Horizons and Plan Memorable Journeys with Singapore Airlines
8. Consider Your Credit Card Benefits
Some premium credit cards offer inherent travel insurance benefits. These can range from rental car insurance to limited trip cancellation and baggage delay coverage. However, these are often supplementary and may not be comprehensive enough, especially for medical emergencies. Always check the specific terms and limits of your card’s benefits carefully.
Comparing Travel Insurance Options: A Quick Overview
Choosing the right policy means understanding the general trade-offs. Here’s a simplified comparison:
| Feature/Policy Type | Basic / Budget Policies | Mid-Range / Standard Policies | Premium / Comprehensive Policies |
|---|---|---|---|
| Price Point | Lowest | Moderate | Highest |
| Trip Cancellation/Interruption | Limited reasons, lower limits | Good coverage, decent limits | Broadest reasons, highest limits |
| Medical & Evacuation | Low limits, often only emergency | Good emergency coverage, higher limits | Highest limits, often includes pre-existing conditions (with waiver) |
| Baggage (Loss/Delay) | Very low limits, high deductibles | Moderate limits, lower deductibles | Highest limits, includes valuables, low/no deductibles |
| Adventure Sports | Generally excluded | Optional add-on, limited sports | Often included or easily added for many sports |
| Ideal For | Budget-conscious, low-risk trips (e.g., short domestic travel) | Most international travelers, families, city breaks | Longer trips, high-value trips, those with medical needs, adventure travelers |
Common Mistakes to Avoid When Choosing Travel Insurance
Even with the best intentions, travelers often stumble in a few key areas when selecting insurance. Avoiding these pitfalls can save you significant hassle and money:
A common mistake is assuming your existing health insurance will cover you abroad. For travelers from the US, this is rarely the case for international trips, and even within the EU, EHIC cards (for EU citizens) offer public healthcare access, but not necessarily private care or emergency repatriation, which can be critical. Always verify your policy’s international coverage and its limitations before you travel.
Another frequent oversight is underinsuring. Opting for the cheapest policy without thoroughly checking the coverage limits can leave you exposed. Imagine a several-thousand-euro medical bill in a foreign hospital and a policy that only covers a fraction of it. It’s a false economy to save a small amount on the premium only to face massive out-of-pocket expenses later.
Failing to declare pre-existing medical conditions is another major pitfall. If you have an existing condition and don’t disclose it, any claim related to that condition will almost certainly be denied, rendering your medical coverage useless. Be transparent with your insurer during the application process to ensure your policy is valid.
Finally, not reading the policy’s fine print, particularly regarding exclusions and claims procedures, is a widespread issue. Many travelers only discover what their policy doesn’t cover when they try to make a claim. For instance, some policies might exclude incidents related to specific adventure activities unless an extra rider is purchased, or they might have strict requirements for reporting theft within a certain timeframe to local police. Always know what you’re covered for and, more importantly, what you’re not.
FAQ: Answering Your Top Travel Insurance Questions
- How far in advance should I buy travel insurance?
It’s best to purchase travel insurance shortly after booking your initial trip components, such as flights or accommodation. This ensures you’re covered for potential trip cancellation due to unforeseen events that might occur between booking and departure. Some benefits, like ‘cancel for any reason’ or pre-existing condition waivers, often require purchase within 10-21 days of your initial trip deposit. - Does travel insurance cover COVID-19 related issues?
Many modern travel insurance policies now offer some form of COVID-19 coverage, but it varies significantly. This might include medical expenses if you contract COVID-19 abroad, or trip interruption if you’re quarantined. Always check the specific policy wording for details on pandemic-related exclusions and inclusions. - What if I need to make a claim while traveling?
Contact your insurance provider as soon as possible. Most have 24/7 emergency hotlines. Keep all relevant documentation: medical reports, police reports for theft, airline delay confirmations, and receipts for any additional expenses incurred. Detailed records simplify the claims process significantly upon your return. - Is travel insurance mandatory for certain countries?
Yes, several countries, particularly within the Schengen Area (which includes Germany, France, Italy, and Spain, among others), require visitors to have travel insurance that covers emergency medical treatment and repatriation, with a minimum coverage of €30,000, to obtain a visa. Always check the specific entry requirements for your destination. - Can I get travel insurance if I’m already traveling?
It’s generally more difficult and often more expensive to purchase travel insurance once your trip has already begun. Some providers offer ‘on-trip’ or ‘post-departure’ policies, but these often have limitations or waiting periods before coverage kicks in, especially for medical benefits. It’s always best to arrange it before you leave.
Making an informed decision about travel insurance is a cornerstone of responsible and affordable travel planning. By understanding your needs, comparing options, and avoiding common pitfalls, you can choose the right coverage for your flights, health, and baggage, ensuring your next adventure is memorable for all the right reasons. Explore more travel guides and tips to enhance your journeys on GoTrendlin.